
Synchronisation of Croatia’s GDP cycle with other former Yugoslav economies
Part 4 compares Croatia’s GDP cycle with the cycles of Bosnia and Herzegovina, Montenegro, North Macedonia, Serbia and Slovenia. Synchronisation matters because economies that move together may share trade exposure, labour-market links, tourism shocks, EU demand conditions, financial channels or regional spillovers. The analysis uses HP-filtered cycles, cross-correlation functions and the concordance index. Table 5 is used for precise lead-lag interpretation, but it is not inserted as a displayed table placeholder.


The visual evidence shows strong synchronisation with Bosnia and Herzegovina, Montenegro and Slovenia. Croatia and Bosnia and Herzegovina share the same broad sequence of phases: pre-crisis expansion, global-financial-crisis downturn, gradual recovery, pandemic contraction and post-pandemic rebound. The pandemic fall is deeper in Croatia, but the timing is closely aligned. Croatia and Montenegro also share major turning points, although Montenegro’s cycle is more volatile, particularly around the pandemic. This is consistent with the importance of tourism-related shocks in both economies, but with stronger amplitude in Montenegro.
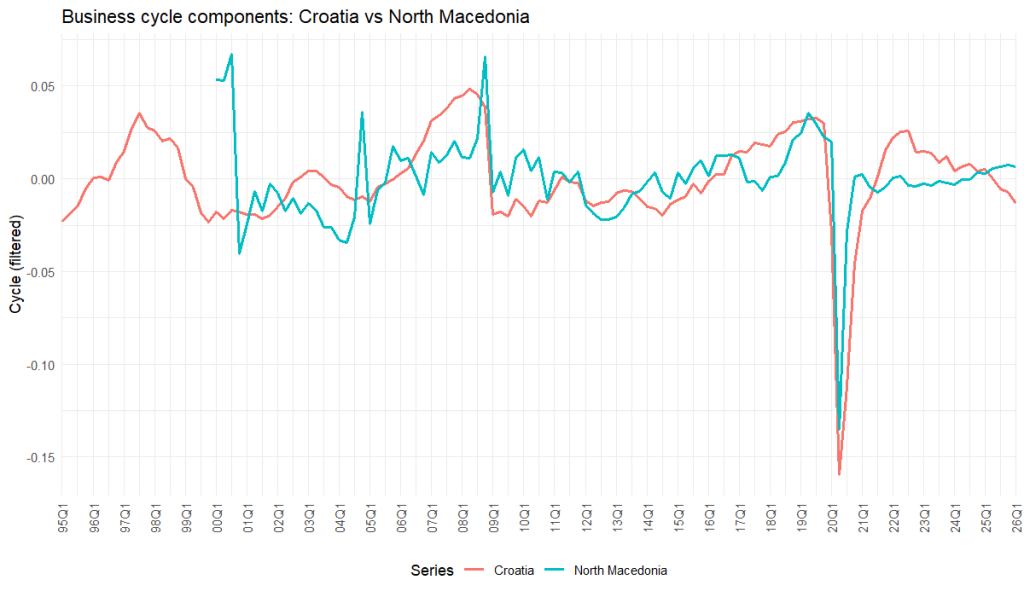


Croatia and Slovenia show a strong common European cycle. The pre-2008 expansion, the crisis downturn, the recovery and the pandemic shock are all visible in both series. Slovenia’s cycle is somewhat smoother in some periods, but the alignment is clear. The comparison with Serbia is meaningful but weaker. The global financial crisis and pandemic are shared, but the cycles are less tightly aligned than in the cases of Bosnia and Herzegovina, Montenegro and Slovenia. North Macedonia is the weakest visual comparison. Some common movements are visible, especially around COVID-19, but the alignment is less stable over the whole sample.

The cross-correlation results support the visual interpretation. Using the file order convention, negative lags are interpreted as the first-named series leading the second, while positive lags suggest the second-named series leading the first. For Croatia and Bosnia and Herzegovina, the zero-lag correlation is about 0.866, the strongest of the pair. Lag -1 is also high, around 0.674, and lag +1 is around 0.614. This means the dominant relationship is contemporaneous, although Croatia may slightly lead Bosnia and Herzegovina in some episodes.

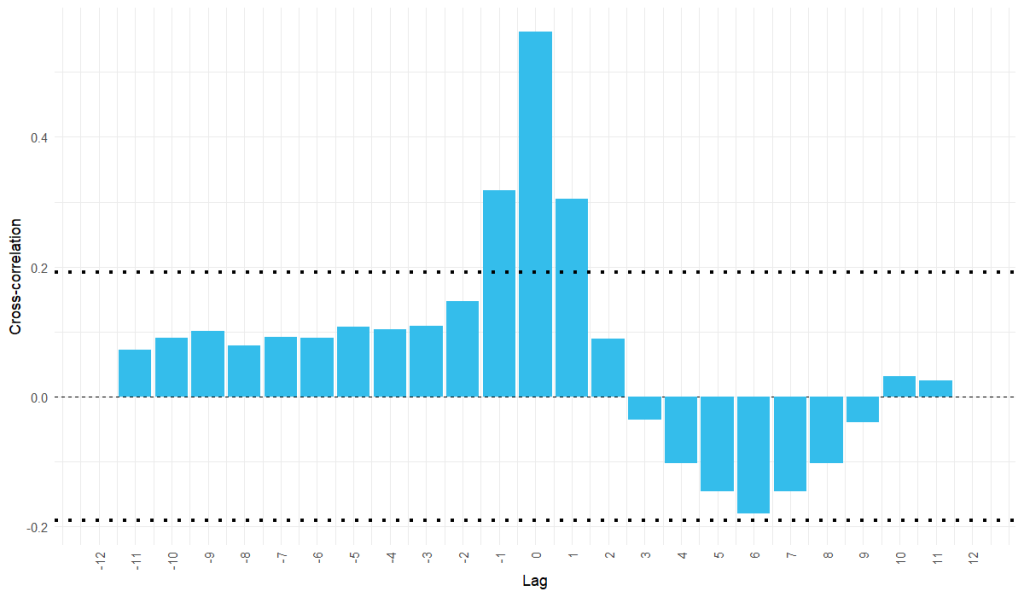
For Croatia and Montenegro, the zero-lag correlation is about 0.829, with lag -1 also high at around 0.714. This again points to strong contemporaneous movement, with a possible one-quarter Croatian lead in some phases. For Croatia and North Macedonia, the zero-lag correlation is lower, about 0.562, and neighbouring lags are much weaker. This suggests common shocks but weaker synchronisation. For Croatia and Serbia, the zero-lag correlation is about 0.505, with lag -1 at about 0.394 and lag +1 at about 0.376. The relationship is meaningful but not especially strong. For Croatia and Slovenia, the zero-lag correlation is about 0.758. The lag +1 correlation, around 0.623, is higher than the lag -1 value, around 0.535, which suggests that Slovenia may lead Croatia slightly in some episodes, although the dominant result is still contemporaneous co-movement.


Table 6 summarises synchronisation using the concordance index. Croatia’s highest concordance is with Bosnia and Herzegovina, at about 0.827. Montenegro follows closely, at about 0.802. Slovenia is also strongly synchronised, with a concordance index of about 0.719. Serbia is moderately synchronised, at about 0.696. North Macedonia is the weakest pair, with a concordance index of about 0.600 and a borderline p-value. This hierarchy is economically plausible. Croatia is most synchronised with economies that share strong regional, tourism, trade or European-cycle exposure. Synchronisation with Serbia is meaningful but weaker, while North Macedonia appears less tightly aligned.
Table 6. Concordance index
| Series1 | Series2 | N | N11 | N00 | Nc | C_index | p_value |
|---|---|---|---|---|---|---|---|
| Croatia | Bosnia and Herzegovina | 104 | 39 | 47 | 86 | 0.827 | 0.000 |
| Croatia | Montenegro | 81 | 35 | 30 | 65 | 0.802 | 0.000 |
| Croatia | North Macedonia | 105 | 29 | 34 | 63 | 0.600 | 0.050 |
| Croatia | Serbia | 125 | 38 | 49 | 87 | 0.696 | 0.000 |
| Croatia | Slovenia | 121 | 37 | 50 | 87 | 0.719 | 0.000 |
The conclusion from Part 4 is that Croatia’s GDP cycle is strongly connected to the region, but not equally to all former Yugoslav economies. Its closest cyclical partners in this exercise are Bosnia and Herzegovina, Montenegro and Slovenia. The relationships with Serbia and North Macedonia are weaker, although still visible. The most important result is that the major regional and European shocks are shared, even when amplitudes and recoveries differ.
Methodological appendix to Part 4
The cross-correlation function measures the relationship between two cyclical series at different leads and lags. A peak at lag zero means that the two cycles move most strongly at the same time. A peak away from zero may suggest that one economy leads or lags the other. The sign of the lag must be interpreted according to the order of the series in the calculation.
The concordance index measures how often two economies are in the same cyclical phase. Each quarter is classified as expansion or contraction for each economy. If both economies are in expansion, or both are in contraction, the quarter is concordant. The index is the share of comparable quarters in which the phases match. A value close to one indicates strong synchronisation, while a value close to one half suggests weak phase alignment. Concordance should be read together with the cycle graphs and cross-correlations, because two economies may share phases while having very different amplitudes.
Overall conclusion
Croatia’s quarterly GDP series from 1995Q1 to 2026Q1 is strongly trending, highly seasonal and persistent. Its long-run path shows a pre-2008 expansion, a prolonged post-crisis weakness, renewed growth, a deep pandemic shock and a strong rebound. The ARIMA model performs well as a short-term forecasting tool, with all holdout observations falling within the reported 80% and 95% prediction intervals. Business-cycle dating confirms the main historical episodes across three filters, although the most recent turning points remain somewhat method-dependent. Regional synchronisation is strongest with Bosnia and Herzegovina, Montenegro and Slovenia, moderate with Serbia and weakest with North Macedonia. The broader message is that Croatia’s GDP cycle should be read both nationally and regionally. Domestic structure matters, especially the role of tourism and services, but the major cyclical movements are deeply connected with the former Yugoslav and wider European macroeconomic environment.
References
Baxter, M., & King, R. G. (1999). Measuring business cycles: Approximate band-pass filters for economic time series. Review of Economics and Statistics, 81(4), 575–593.
Corbae, D., & Ouliaris, S. (2006). Extracting cycles from nonstationary data. Econometric Theory, 22(4), 843–858.
Eurostat. (n.d.). Gross domestic product and main components — quarterly national accounts (namq_10_gdp).
Harding, D., & Pagan, A. (2002). Dissecting the cycle: A methodological investigation. Journal of Monetary Economics, 49(2), 365–381.
Hodrick, R. J., & Prescott, E. C. (1997). Postwar U.S. business cycles: An empirical investigation. Journal of Money, Credit and Banking, 29(1), 1–16.
Hyndman, R. J., & Athanasopoulos, G. (2025). Forecasting: Principles and Practice.
U.S. Census Bureau. (2025). X-13ARIMA-SEATS Seasonal Adjustment Program.
