
Part 1. A Persistent Economy with Moderate Seasonality
North Macedonia’s GDP as a quarterly time series
Gross domestic product is the broadest single indicator of macroeconomic activity. It measures the value of goods and services produced in an economy and therefore provides a compact summary of long-run expansion, recession, recovery and cyclical instability. In this blog post, North Macedonia’s GDP is analysed as a quarterly index, with 2021=100, covering the period from 2000Q1 to 2026Q1. The data source is Eurostat’s quarterly national accounts dataset, namq_10_gdp. Two versions of the series are examined: the original series and the seasonally adjusted series obtained using X13-ARIMA.
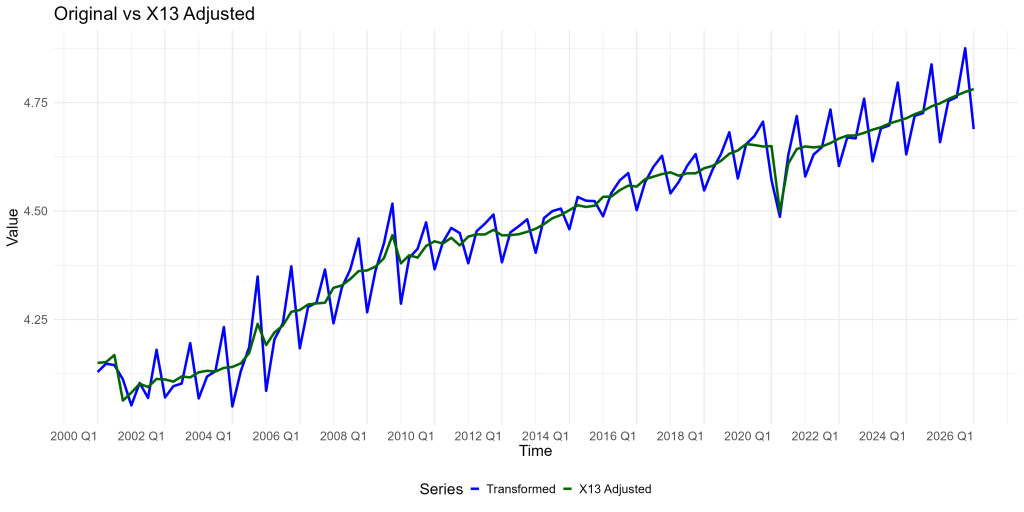
Figure 1 shows a long upward movement in North Macedonia’s GDP, but the path is not uniform. The early 2000s begin from a relatively low base and show gradual expansion. The mid-2000s bring a clearer upward phase, which continues until the global financial crisis. Around 2008–2009, the earlier expansion is interrupted, although the break is less visually dramatic than the COVID-19 shock later in the sample. After the global financial crisis, the series resumes growth, but the path is uneven. The 2010s are characterised by continued expansion with several periods of moderation rather than by a single uninterrupted boom.
The COVID-19 shock is visible in 2020 as a sharp fall, followed by a recovery. Compared with highly tourism-sensitive economies such as Montenegro and Croatia, the pandemic movement appears less extreme, but it is still one of the clearest interruptions in the series. In the latest observations, GDP is at a historically high level. The final quarters suggest continued expansion rather than renewed contraction, although the pace looks more moderate than a post-crisis rebound.
The comparison between the original and the seasonally adjusted series is important. Quarterly GDP contains repeated within-year patterns, and the original series shows clear seasonal movement. Seasonal adjustment removes predictable calendar effects and makes it easier to interpret the underlying trend and cycle. In North Macedonia’s case, seasonality is significant but not as visually dominant as in Montenegro or Croatia. This means that the seasonally adjusted series is still essential for macroeconomic interpretation, but the main story is persistence and trend growth rather than seasonal amplitude alone.
Figures 2 and 3 show how persistent the series is before and after differencing. The autocorrelation function of the log-level series remains strongly positive across many lags. The first autocorrelation is about 0.892, which means that GDP in one quarter is closely related to GDP in the previous quarter. This is typical for a macroeconomic level variable. GDP is not a random sequence of quarterly observations. It reflects capital accumulation, employment, productivity, institutions, external demand and policy conditions, all of which tend to evolve gradually.
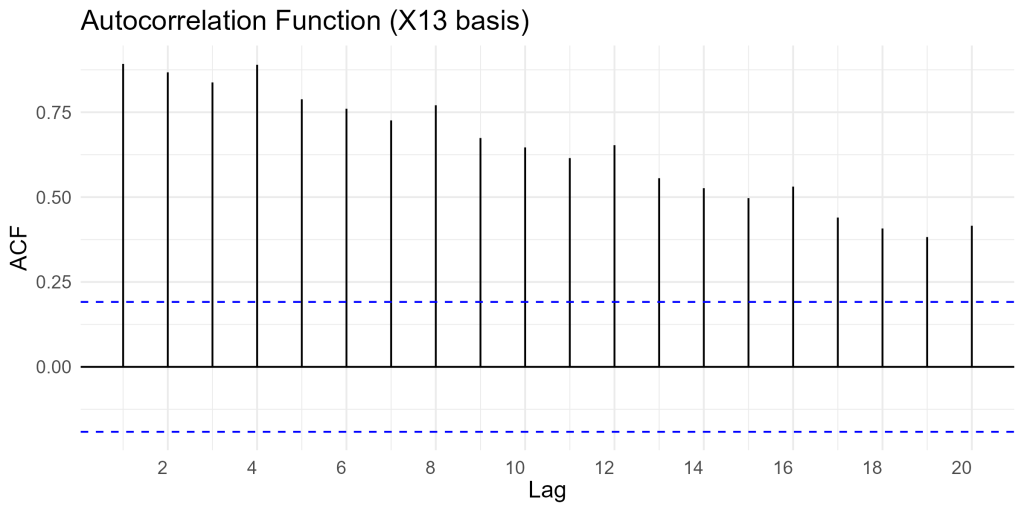
Figure 3 changes the picture substantially. After applying first and seasonal differences to the log series, autocorrelation becomes much weaker, and the first differenced autocorrelation is negative, around -0.507. The second-difference autocorrelation is even more negative, around -0.673. This suggests that differencing removes the dominant persistent structure and reveals shorter-run adjustment dynamics. In practical terms, the log-level series is useful for describing the long-run development of the economy, while the differenced series is more suitable for short-term modelling.
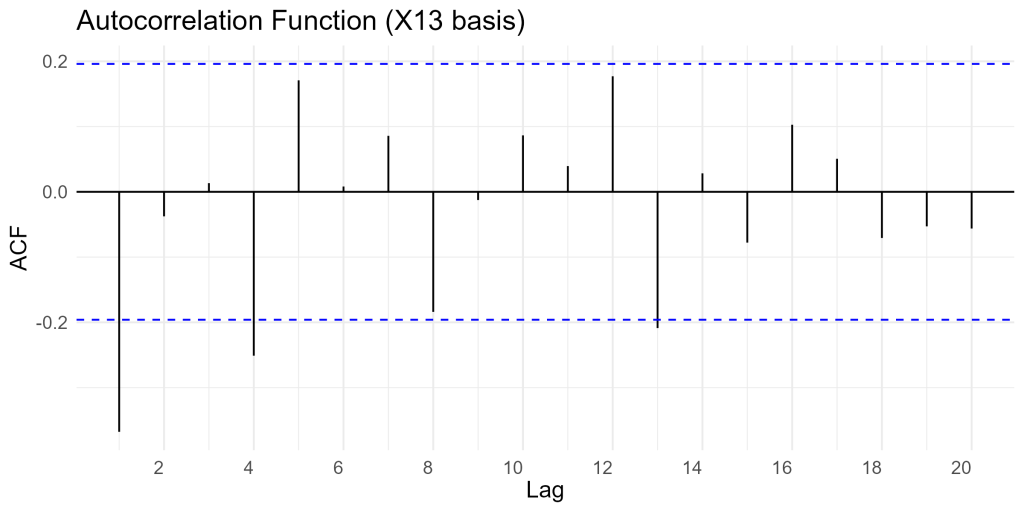
Table 1 confirms that North Macedonia’s GDP is a structured and persistent time series. Trend strength is very high, around 0.992, indicating that the long-run component dominates the series. Seasonal strength is also high, around 0.889, confirming that seasonal adjustment is necessary. The seasonal indicators point to a regular within-year profile, with a reported seasonal trough early in the year. Spikiness is extremely low, meaning that the series is not dominated by isolated random spikes. Even the pandemic shock appears within a structured time-series path rather than as a purely erratic movement.
Table 1. Features of GDP for North Macedonia time series
| Feature | Value |
|---|---|
| trend_strength | 0.992 |
| seasonal_strength_year | 0.889 |
| seasonal_peak_year | 0 |
| seasonal_trough_year | 1 |
| spikiness | 0.000 |
| linearity | 2.054 |
| curvature | -0.230 |
| stl_e_acf1 | -0.375 |
| stl_e_acf10 | 0.271 |
| acf1 | 0.892 |
| acf10 | 6.235 |
| diff1_acf1 | -0.507 |
| diff1_acf10 | 2.312 |
| diff2_acf1 | -0.673 |
| diff2_acf10 | 3.352 |
| season_acf1 | 0.890 |
| pacf5 | 1.482 |
| diff1_pacf5 | 1.113 |
| diff2_pacf5 | 1.232 |
| season_pacf | 0.501 |
| zero_run_mean | 0.000 |
| nonzero_squared_cv | 0.002 |
| zero_start_prop | 0.000 |
| zero_end_prop | 0.000 |
| lambda_guerrero | 2.000 |
| kpss_stat | 2.118 |
| kpss_pvalue | 0.010 |
| pp_stat | -1.719 |
| pp_pvalue | 0.100 |
| ndiffs | 1 |
| nsdiffs | 1 |
| bp_stat | 83.616 |
| bp_pvalue | 0.000 |
| lb_stat | 86.028 |
| lb_pvalue | 0.000 |
| var_tiled_var | 0.008 |
| var_tiled_mean | 0.951 |
| shift_level_max | 0.070 |
| shift_level_index | 19 |
| shift_var_max | 0.011 |
| shift_var_index | 17 |
| shift_kl_max | 0.183 |
| shift_kl_index | 3 |
| spectral_entropy | 0.366 |
| n_crossing_points | 7 |
| longest_flat_spot | 5 |
| coef_hurst | 0.993 |
| stat_arch_lm | 0.927 |
The linearity measure is positive and relatively large, while curvature is negative. This suggests a rising long-term trajectory, but not one that proceeds at a constant rate. The STL residual autocorrelation is negative at the first lag but positive over longer lags, which means that some structure remains even after decomposition. The ACF and PACF features show strong persistence in levels and weaker but still meaningful dependence after differencing. The seasonal autocorrelation is about 0.890, again supporting the importance of quarterly seasonal structure.
The stationarity diagnostics point clearly toward non-stationarity in the level series. The KPSS statistic is high, with a p-value at the lower bound, and the automatic differencing indicators recommend one ordinary difference and one seasonal difference. The Phillips-Perron p-value is at the upper bound, which does not overturn the broader conclusion: the level series behaves like a persistent, non-stationary macroeconomic series. The Box-Pierce and Ljung-Box statistics are highly significant in levels, confirming strong serial dependence before modelling. The variance and shift indicators show meaningful changes in level and distribution, especially in the early and mid-sample. Spectral entropy is moderate-low, around 0.366, meaning that the series is structured rather than noisy. The number of crossing points is limited, the longest flat spot is short, and the Hurst coefficient is close to one, confirming strong long-memory behaviour. The ARCH statistic is not large enough to make volatility clustering the central feature of the series.
The main conclusion from Part 1 is that North Macedonia’s GDP is a strongly trending, persistent and seasonally structured quarterly series. The long-run path is upward, interrupted by the global financial crisis and COVID-19, but the dominant statistical feature is persistence rather than erratic volatility. These properties justify the use of log transformation, seasonal adjustment, differencing and ARIMA modelling.
Methodological appendix to Part 1
Graphical exploration is the first step in time-series analysis. It helps identify trend, seasonality, cyclical movement, structural breaks, changes in volatility and outliers. In quarterly GDP data, the main risk is confusing normal seasonal movement with genuine macroeconomic change. Another risk is over-interpreting one unusual observation without checking whether it belongs to a broader pattern.
A log transformation is often useful when macroeconomic fluctuations become larger in absolute terms as the level of the series rises. Logs make movements easier to interpret as approximate percentage changes. First differences focus on short-run change, while seasonal differences compare a quarter with the same quarter in the previous year and help remove recurring seasonal patterns.
The features in Table 1 summarise the statistical behaviour of the series. Trend strength, seasonal strength, autocorrelation, stationarity tests, entropy, spikiness, shift measures and persistence indicators jointly show whether a series is trending, seasonal, persistent, noisy or structurally unstable. For North Macedonia, the dominant message is strong persistence, high trend strength and meaningful seasonality.