ARIMA estimation and short-term forecasting
Part 2 moves from description to forecasting. Since Part 1 showed that North Macedonia’s GDP is persistent, seasonal and non-stationary in levels, the natural question is whether a statistical model can use that structure to forecast the near future. The ARIMA model used here is estimated on the transformed series and evaluated over an eight-quarter holdout period. This is a statistical forecasting exercise, not a structural macroeconomic model. It does not explain GDP through consumption, investment, exports, public spending or external demand. It asks whether the past behaviour of the series itself contains enough information for short-term projection.
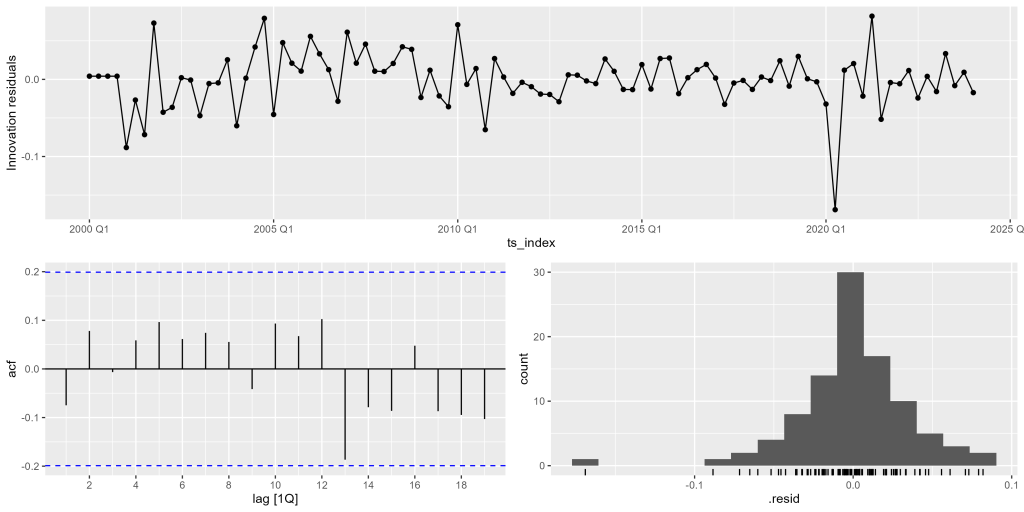
Table 2 reports an ARIMA model with an autoregressive coefficient of about 0.417, a first seasonal autoregressive coefficient of about -0.282, a second seasonal autoregressive coefficient of about -0.215 and a positive constant of about 0.0216. The ordinary autoregressive coefficient is statistically significant, which confirms that recent past movements contain useful information about the next observations. The first seasonal autoregressive term is also statistically significant, while the second seasonal autoregressive term is close to conventional significance. This structure is consistent with the evidence from Part 1: persistence matters, but seasonal dynamics also matter.
Table 2. ARIMA model estimation and parameters accuracy
| Model | arima | ets | naive | snaive |
|---|---|---|---|---|
| sigma2 | 0.001 | 0.001 | 0.008 | 0.002 |
| log_lik | 176.563 | 100.314 | NA | NA |
| AIC | -343.126 | -180.628 | NA | NA |
| AICc | -342.436 | -178.070 | NA | NA |
| BIC | -330.463 | -154.881 | NA | NA |
| MSE | NA | 0.001 | NA | NA |
| AMSE | NA | 0.001 | NA | NA |
| MAE.x | NA | 0.026 | NA | NA |
| lb_stat | 3.826 | 7.597 | 207.444 | 14.428 |
| lb_pvalue | 0.575 | 0.180 | 0.000 | 0.013 |
| .type | Test | Test | Test | Test |
| ME | 0.014 | 0.021 | 0.122 | 0.049 |
| RMSE | 0.018 | 0.027 | 0.140 | 0.053 |
| MAE.y | 0.015 | 0.022 | 0.122 | 0.049 |
| MPE | 0.297 | 0.446 | 2.555 | 1.032 |
| MAPE | 0.306 | 0.459 | 2.555 | 1.032 |
| ACF1 | -0.342 | -0.327 | -0.434 | 0.510 |
| estimate__ar1 | 0.417 | NA | NA | NA |
| std.error__ar1 | 0.104 | NA | NA | NA |
| statistic__ar1 | 4.004 | NA | NA | NA |
| p.value__ar1 | 0.000 | NA | NA | NA |
| estimate__sar1 | -0.282 | NA | NA | NA |
| std.error__sar1 | 0.114 | NA | NA | NA |
| statistic__sar1 | -2.484 | NA | NA | NA |
| p.value__sar1 | 0.015 | NA | NA | NA |
| estimate__sar2 | -0.215 | NA | NA | NA |
| std.error__sar2 | 0.110 | NA | NA | NA |
| statistic__sar2 | -1.954 | NA | NA | NA |
| p.value__sar2 | 0.054 | NA | NA | NA |
| estimate__constant | 0.022 | NA | NA | NA |
| std.error__constant | 0.004 | NA | NA | NA |
| statistic__constant | 5.686 | NA | NA | NA |
| p.value__constant | 0.000 | NA | NA | NA |
The positive constant is highly significant and captures the underlying upward drift in the transformed series. Economically, the model says that North Macedonia’s GDP combines gradual growth with short-run persistence and seasonal adjustment. The autoregressive coefficient is not as high as in some smoother GDP series, which suggests that the model is not simply extrapolating a near-random-walk level. It allows for more short-run correction and seasonal structure.
The residual diagnostics are acceptable. The Ljung-Box p-value for the ARIMA model is about 0.575, so the residual autocorrelation test does not reject the adequacy of the model at conventional significance levels. Figure 4 supports this interpretation. Most residuals fluctuate around zero, although some large disturbances remain visible, especially around periods of major macroeconomic stress. The residual autocorrelation is negative at the first lag, but not large enough to undermine the model’s use as a short-term forecasting tool.
The model comparison in Table 2 is favourable to ARIMA. The ARIMA model has a holdout MAPE of about 0.306%, which is lower than the ETS model, the naive model and the seasonal naive model. It also has the lowest RMSE and MAE among the reported benchmark models. This is important because a forecasting model should not only fit the training sample; it should outperform simple alternatives. In this case, ARIMA provides a clearly better short-term statistical benchmark than using the previous observation or the same quarter from the previous year.
Figure 5 and Table 3 show the eight-quarter forecast from 2024Q2 to 2026Q1. The forecast preserves the seasonal profile of the GDP index, including higher fourth-quarter values and lower first-quarter values. This is important because the seasonal pattern is a meaningful feature of the series. All actual holdout observations fall inside both the 80% and 95% prediction intervals. This is a strong practical result. It means that the model’s uncertainty bands are sufficiently wide to contain the realised path, but still narrow enough to be useful.
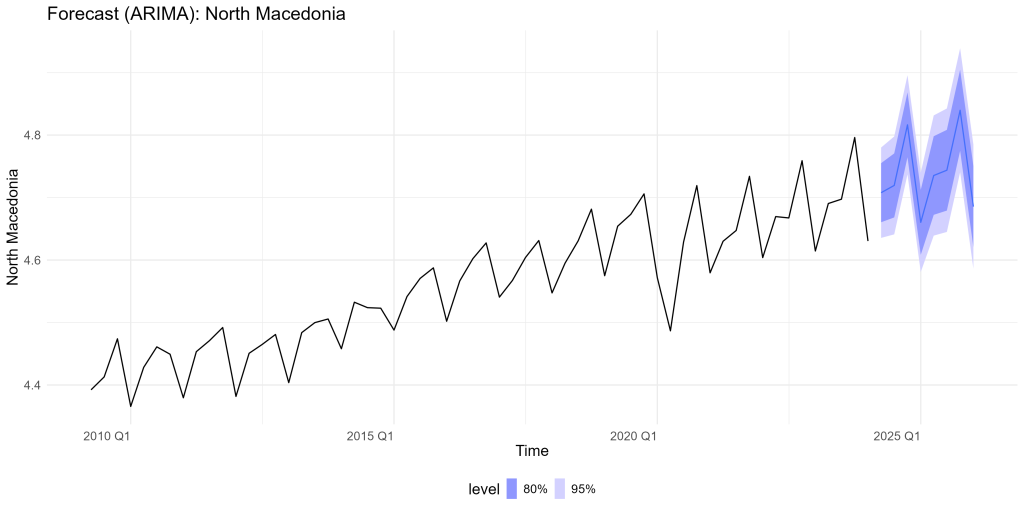
The point forecasts are reasonably close to the actual values. In 2024Q2, the actual value is 112.122 and the forecast mean is 110.806. In 2024Q4, the actual value is 126.231 and the forecast mean is 123.523. In 2025Q1, the actual value is 105.491 and the forecast mean is 105.671. In 2026Q1, the actual value is 108.717 and the forecast mean is 108.367. The largest visible gap occurs in 2025Q4, where the actual value is 131.005 and the forecast mean is 126.439, but even this observation remains inside the 80% and 95% intervals. This suggests that the model slightly underestimates some of the stronger later observations, but not enough to invalidate the forecast.
Table 3. Forecast eight quarters ahead — ARIMA model
| Date | Actual | Mean | Lower 80% | Upper 80% | Lower 95% | Upper 95% |
|---|---|---|---|---|---|---|
| 2024 Q2 | 112.1 | 110.8 | 105.7 | 116.2 | 103.1 | 119.1 |
| 2024 Q3 | 112.8 | 112.1 | 106.5 | 118.0 | 103.7 | 121.2 |
| 2024 Q4 | 126.2 | 123.5 | 117.3 | 130.1 | 114.1 | 133.7 |
| 2025 Q1 | 105.5 | 105.7 | 100.3 | 111.3 | 97.6 | 114.4 |
| 2025 Q2 | 116.0 | 113.9 | 107.0 | 121.3 | 103.5 | 125.4 |
| 2025 Q3 | 117.1 | 114.9 | 107.7 | 122.5 | 104.1 | 126.8 |
| 2025 Q4 | 131.0 | 126.4 | 118.5 | 134.9 | 114.5 | 139.6 |
| 2026 Q1 | 108.7 | 108.4 | 101.6 | 115.6 | 98.1 | 119.7 |
The practical conclusion is that ARIMA is a credible short-term forecasting tool for North Macedonia’s GDP. It captures persistence, seasonal structure and the recent upward path well enough to outperform the reported alternatives. However, it remains a baseline statistical forecast. If a new shock appears, the model will only recognise it after it enters the data. For economic interpretation, ARIMA should therefore be combined with information about domestic demand, external conditions, prices, policy and regional developments.
Methodological appendix to Part 2
ARIMA stands for autoregressive integrated moving average. The autoregressive part uses past values, the integrated part uses differencing to handle non-stationarity, and the moving-average part uses past shocks or forecast errors. Seasonal ARIMA models extend this logic to recurring quarterly patterns. In this exercise, the series is split into a training sample and an eight-quarter holdout sample. The model is estimated on the training data and evaluated on observations not used in estimation. Forecast accuracy is assessed using RMSE, MAE and MAPE. RMSE penalises large errors more heavily, MAE measures average absolute error and MAPE expresses error as a percentage of the observed value. Residual diagnostics, especially the Ljung-Box test, check whether the model has left systematic autocorrelation unexplained. For North Macedonia, the ARIMA model performs well both diagnostically and in the holdout comparison.